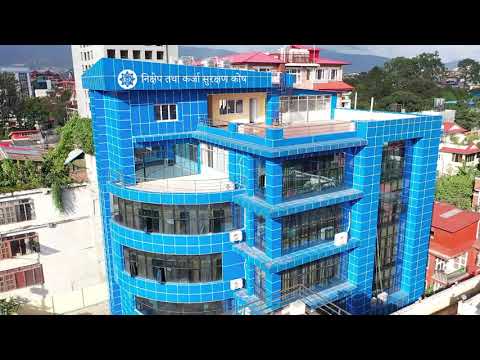

The Deposit and Credit Guarantee Fund (DCGF - Nikshep Tatha Karja Surakshan Kosh - निक्षेप तथा कर्जा सुरक्षण कोष), initially established as the Credit Guarantee Corporation on September 20, 1974, is a pivotal entity in Nepal's financial landscape. It came into existence through the combined efforts and financial backing of Nepal Rastra Bank, Rastriya Banijya Bank, and Nepal Bank Limited. The fund was initially set up with an authorized capital of 10 million and a paid-up capital of 3 million. However, following the introduction of the Deposit and Credit Guarantee Fund Act in 2017, not only did its name change to DCGF but its authorized and paid-up capital also experienced a significant boost, reaching 10 billion.
Over the years, DCGF has expanded its services and streamlined its operations. Initially, it focused on supporting priority sector lending for Rastriya Banijya Bank and Nepal Bank Limited, with a cap of 2.50 million. Presently, DCGF operates in several sectors:
Deposit Guarantee
Credit Guarantee, which includes:
Micro Finance and Deprived Sector Credit Guarantee
Agricultural Credit Guarantee
Educational Credit and Educated Unemployment Business Credit Guarantee
Small and Medium Enterprises Credit Guarantee
Livestock Guarantee
The Deposit Guarantee is a government-backed program designed to safeguard public savings. It is crucial in strengthening public confidence in the banking system, encouraging money flow into formal banking channels, and facilitating economic growth.
Ensures the protection of depositor interests
Contributes to financial system stability
Shields small depositors' funds
Enhances competitiveness in the financial sector
Reduces dependency on state funds for financial bailouts
The Credit Guarantee scheme is a national initiative to enhance financial accessibility for underprivileged and marginalized communities. It provides banks and financial institutions with a safety net for investments made in these sectors.
Motivates banks to finance high-risk and deprived sectors
Aids in providing financial access to remote regions
Offers banking facilities to the underprivileged
Addresses capital shortages in banks
Fosters self-employment opportunities
Contributes to poverty reduction
Supports overall economic development of the nation
Financial stability is paramount for stakeholders, including central banks, governments, market players, borrowers, and deposit insurers. In this context, the Deposit and Credit Guarantee Fund (DCGF) in Nepal has played a significant role since the inception of its deposit guarantee scheme in 2010.
Deposit guarantee, or deposit insurance, is globally acknowledged as vital to a country’s financial safety net. Implemented in over 120 countries, it protects depositors by securing guaranteed deposits in banks and financial institutions (BFIs). This protection is especially crucial in the unlikely event of a BFI's failure.
Under the Deposit and Credit Guarantee Fund Act of 2073, DCGF is statutorily responsible for both deposit and credit guarantee functions. Its governance features a board with six government representatives and one from Nepal Rastra Bank, emphasizing its nature as a government-sponsored and administered entity.
In Nepal, the deposit guarantee scheme applies to various types of BFIs:
Commercial Banks
Development Banks
Finance Companies
Micro Finance Institutions
DCGF has set a premium rate of 0.16% on guaranteed deposits for all member BFIs. The deposit guarantee coverage is Rs 5,00,000 per natural individual depositor per member institution, and it applies to a combination of savings and fixed deposits.
This scheme provides a safety cushion for individual depositors and enhances public confidence in the financial system. Securing deposits up to a certain limit mitigates the risk of bank runs and maintains stability in the financial sector. Moreover, the involvement of various financial institutions under this scheme reflects Nepal's comprehensive approach to financial safety.
DCGF's deposit guarantee scheme is critical to maintaining Nepal's financial stability. It reassures depositors and strengthens the overall trust in the banking system, contributing significantly to the country's economic resilience.
The Deposit and Credit Guarantee Fund (DCGF) plays a vital role in safeguarding the deposits of individuals in Nepal, fostering confidence in the country's financial system. Here are the key elements of the deposit guarantee provided by DCGF:
DCGF guarantees deposits up to Rs. 5 lakhs for natural person depositors.
This guarantee applies to deposits held with commercial banks and financial institutions licensed by Nepal Rastra Bank.
The premium rate for the deposit guarantee is set at 0.16% annually.
This premium is paid every quarter, calculated at 0.04%.
The calculation is based on the average deposit amount over the last three months of each quarter.
Preparation of Depositors’ List: In the event of a bank or financial institution's liquidation, the appointed liquidator prepares a list of depositors eligible for compensation.
Submission to DCGF: This list is then submitted to DCGF.
Compensation Payment: DCGF receives the list and pays the compensation amount to the depositors concerned. The liquidator facilitates this payment.
A Class Commercial Banks: 21 members
B Class Development Banks: 17 members
C Class Finance Companies: 17 members
D Class Micro Finance Institutions: 2 members
This deposit guarantee scheme by DCGF is instrumental in:
Protecting Individual Depositors: Guaranteeing deposits up to a certain limit protects individual depositors from total loss in the event of failures at financial institutions.
Strengthening Financial Stability: The scheme contributes to the overall stability of the financial system by preventing panic withdrawals and maintaining depositor confidence.
Promoting Responsible Banking Practices: The requirement of a premium payment encourages financial institutions to manage risks effectively.
The Deposit and Credit Guarantee Fund (DCGF) offers a range of credit guarantee schemes to bolster various sectors in Nepal. These schemes are crucial in providing financial security and promoting economic development. Here's a detailed look at each scheme:
Guarantee Limit: Loans for livestock purchases up to Rs. 1,50,000.
Premium Rate: 5% annually, with the loanee paying 1% and the Government of Nepal subsidizing 4%.
Compensation:
90% of the guaranteed amount in case of livestock death during the policy period.
50% compensation for unproductive livestock.
Guarantee Limits:
Up to Rs. 1 million under group or individual guarantee.
Up to Rs. 2 million with collateral.
Up to Rs. 1.5 million for women entrepreneurs' micro-enterprises.
Up to Rs. 1 million for Dalits and skilled foreign returnees.
Premium Rate: 0.8% annually, with 50% covered by the member institution and 50% subsidized.
Claim Tenure: Claims must be lodged within two years of the loan's due date.
Compensation: 75% of the loan's outstanding balance at the due date.
Guarantee Limit: Up to Rs. 10 million, with prior approval required for loans above Rs. 10 million to Rs. 30 million.
Premium Rate: 0.6% annually, equal sharing between the member institution and government subsidy.
Claim Tenure: Maximum of two years from the loan's due date.
Compensation:
80% for loans up to Rs. 5 million.
70% for loans above Rs. 5 million to Rs. 30 million.
Guarantee Limit: Up to Rs. 10 million, with approval needed for loans above this up to Rs. 30 million.
Premium Rate: 0.6% annually, 50% subsidized.
Compensation:
80% for loans up to Rs. 5 million.
70% for loans over Rs. 5 million and up to Rs. 30 million.
Guarantee Limit: Up to Rs. 1 million for education loans and Rs. 5 lakh for business loans to educated unemployed individuals.
Premium Rate: 1% annually, with a 50% subsidy.
Compensation: Up to 80% of the loan's outstanding balance at the due date.
Guarantee Limit: Up to Rs. 30 million for export-oriented businesses, with prior approval for loans above Rs. 5 million.
Premium Rate: 1% annually, with a 50% subsidy.
Compensation:
80% for loans up to Rs. 1 million.
70% for loans over Rs. 1 million up to Rs. 30 million.
These diverse guarantee schemes by DCGF are instrumental in:
Enhancing Financial Accessibility: They make securing loans easier for individuals and businesses in various sectors.
Risk Mitigation: These schemes encourage lending to otherwise considered risky sectors by providing a safety net.
Economic Empowerment: These schemes, from agriculture to SMEs, significantly contribute to the economic empowerment of various segments of society.